Payactiv
On-demand pay and beyondFinanceVerified
- 9.10K Reviews
- 4.4
- Downloads
- 1,000,000+
- Price
- Free
Screenshots
 Analysis by Appwesome
Payactiv is a finance app I would describe as a practical bridge between work already completed and the day a regular paycheck arrives. Its main purpose is to help eligible workers access earned wages early, while also supporting broader money-management goals. That sounds simple, but the real value depends on how clearly the app presents information, how comfortable it is to use in different situations, and whether early access actually solves a problem rather than encouraging a permanent cycle of advances.
I reviewed it with those questions in mind. Payactiv is free, available to everyone by age rating, and developed by On-demand pay and beyond. It has been around since June 4, 2014, and the current version is 2.2.8 for devices running OS 10 or later. Its presence on more than a million devices and an average rating of 4.4 from roughly forty-five thousand ratings suggest that many people find the basic idea useful, although popularity alone does not tell me whether it will fit your employer, payroll setup, or personal habits.
How the app feels to read and navigate
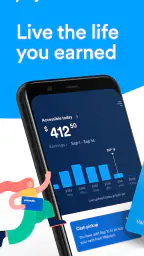
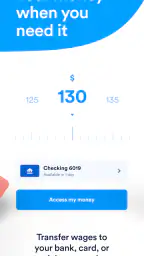
My first impression of a wage-access app is usually shaped less by decoration and more by whether I can quickly answer three questions: what money is available, when it can arrive, and what action I need to take. Payactiv works best when it keeps those answers close to the front of the experience. Someone opening the app after a shift is not looking for a complicated financial dashboard; they want a clear view of their situation and a straightforward next step.
That focus matters for users who are tired, distracted, or checking their balance between other tasks. A well-organized screen can reduce the mental effort involved in deciding whether to request funds. I found that the app’s purpose is easier to understand than that of a traditional banking app because it is centered on earned pay rather than a long list of unrelated account products.
Still, clarity in this category is not only about large numbers or simple menus. The wording around eligibility, timing, transfer choices, and any applicable conditions deserves careful reading. I would not tap through a wage request as casually as I would check a bank balance. Before confirming anything, I would pause to identify the amount being accessed, the expected delivery timing, and whether the action affects the next normal payday.
That is one of my most important practical tips: use the app as a planning tool, not just an emergency button. If you open it only when a bill is due, you may focus on speed and overlook the longer effect on your cash flow. A better routine is to check it when you have time to read the details, then decide whether early access is genuinely necessary.
For people who prefer plain, direct interfaces, Payactiv’s narrow purpose is an advantage. It does not ask me to learn an entire investing platform or decode a complex budgeting system before I can understand the central function. On the other hand, users who expect the same depth as a full-service bank may find the experience limited. This is an earned-wage tool first, not a replacement for every financial service on a phone.
Other Stories to Read




Reading financial information without rushing
Money screens can be stressful even when the design is technically simple. The most helpful approach is to treat every figure as part of a decision rather than as a promise of extra income. Early wage access changes timing; it does not increase what I earn. That distinction should remain visible in my own thinking whenever I use the app.
I also recommend reviewing the app when the phone is held at a comfortable distance and the screen is free from glare. This sounds ordinary, but it makes a difference when the information includes several amounts or explanatory lines. If you use larger system text, magnification, or another display adjustment, check that important labels still remain understandable and that no confirmation detail becomes easy to miss.
Payactiv is likely to suit readers who want a focused path to earned wages, but the experience still requires financial attention. A clean interface cannot decide whether a request is wise for me. I have to connect the amount shown in the app with rent, groceries, transport, subscriptions, and the next pay cycle.
Motor and sensory considerations in everyday use
Early-pay decisions often happen in imperfect conditions: standing in a shop, holding a child, commuting, or using a phone with one hand. That makes touch accuracy and short, understandable steps more important than they might be in a desktop banking session. I prefer to complete a request when I can use both hands and concentrate, especially if the final action moves money rather than merely displaying information.
For users with limited dexterity, the best strategy is to avoid making the request during a rushed moment. Put the phone down, enlarge the view if needed, and give yourself time to confirm each choice. A financial app should not be treated like a quick social-media interaction. A slower, deliberate workflow is a strength here, because it reduces the chance of tapping the wrong amount or overlooking a delivery detail.
People with visual sensitivities may also benefit from controlling the surrounding conditions. Bright outdoor light, reflections, and small interface elements can make a short task feel much harder. I would use Payactiv in a quiet, stable setting whenever possible and rely on the phone’s built-in display and accessibility controls where they help. I would not assume that every visual or motor need is handled automatically by the app itself.
For users who depend on screen readers, voice control, switch access, or other assistive technologies, the sensible approach is to test the key path before relying on it for an urgent bill. Open the app, locate the earned-pay information, move through the request process, and see whether labels and confirmation states are announced in a useful order. That kind of personal check is more reliable than assuming that a finance app will behave perfectly with every device setting.
There is a trade-off between speed and confidence. Someone with no accessibility concerns may finish a routine check quickly, while someone who needs extra navigation time may prefer to plan ahead. In my view, that is not a reason to dismiss Payactiv, but it is a reason not to wait until the last minute. If a payment is due tonight, an app that requires careful verification may be less suitable than a payment method already arranged in advance.
Why context changes the experience
Payactiv is most useful when I understand the surrounding payroll arrangement. The app can be attractive to a worker whose employer and pay setup support the service, but it is not a universal way to pull money from any job. Before depending on it, I would confirm that my employment situation is compatible and that the amount displayed reflects current earned wages rather than an assumption about future income.
This is especially important for people with variable schedules. A worker whose hours change from week to week may see a different available amount than expected. Someone with overtime, shift changes, or recently updated payroll information should treat the displayed figure as a current snapshot and check it before making a commitment. The app can help reveal what is available, but it cannot remove the uncertainty of irregular work.
Consider a realistic example. Imagine I finish a shift and discover that a utility payment is due before my normal payday. Payactiv may give me a way to address the gap using wages I have already earned, which could be more useful than overdrawing a bank account or putting the bill on a credit card. I would open the app, review the available amount and timing, request only what the bill requires, and then note how that decision affects the next paycheck.
The important part of that scenario is the final step. I would not treat the advance as spare money. I would update my personal budget immediately so the next payday is not a surprise. This is a less obvious but valuable workflow: pair every early-access request with a written adjustment to upcoming spending. Without that habit, convenience can hide the fact that the same earnings are arriving earlier.
The app can also make sense for workers who face occasional timing problems rather than constant shortages. A one-off transport repair, a necessary household purchase, or a bill that falls awkwardly between paydays may be easier to manage with earned wages than with high-cost borrowing. For someone regularly short before every payday, however, the better answer may be a broader budget review, a conversation with an employer, or a lower-cost financial product that addresses the underlying gap.
How it compares with ordinary alternatives
The usual alternatives each solve a different part of the problem. A standard bank account keeps money available once payday arrives, but it normally does not change the timing of wages. A credit card can cover an immediate purchase, yet it creates a balance that may carry interest. An overdraft may be fast, but fees and repayment pressure can make it a poor fallback. Payactiv’s main distinction is that it is tied to earned wages, so the decision is about accessing income sooner rather than borrowing against an unrelated credit limit.
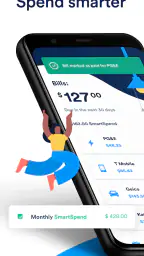
That distinction does not automatically make it the best choice. If I can wait until payday, waiting is simpler and avoids turning a timing issue into another money-management task. If I need a long repayment period, a wage-access app is not designed for that purpose. If I need a complete view of spending, savings, bills, and accounts, a dedicated budgeting or banking app may offer a broader picture.
Where Payactiv stands out is the narrow moment between work completed and pay received. It can be more relevant than a general finance app when the immediate question is, “Can I use part of what I have already earned?” The trade-off is that this convenience depends on the employment and payroll context, while a normal bank account remains useful regardless of which employer processes the paycheck.
Remaining barriers I would consider before relying on it
The largest barrier is not necessarily navigation; it is eligibility and personal cash-flow discipline. A person may install Payactiv expecting instant access, then discover that the useful experience depends on how their workplace handles payroll. That makes it important to treat the first setup as an evaluation period rather than assuming the app will work exactly like a bank account.
I would also pay close attention to every confirmation screen. Early access can feel like a benefit because the money has already been earned, but the timing of the next regular payment still matters. Before accepting an amount, I would ask myself whether the request solves a specific problem, whether I can manage the reduced later balance, and whether waiting would be less stressful overall.
Another barrier is urgency. An app can be easy to understand in a calm room and difficult to use when a payment is about to fail. Users with motor, visual, cognitive, or sensory needs should build in extra time and test their preferred phone settings before an emergency. If the process is hard to complete privately or comfortably, a different arrangement may be more dependable for critical bills.
Privacy and device habits deserve common-sense attention too. I would avoid requesting wages on a shared phone or while someone is watching the screen, and I would keep the device protected with its normal security settings. Financial information is personal, so convenience should not lead me to ignore basic phone security or leave a confirmation screen visible in public.
Finally, I would not use the app as evidence that my budget is healthy. A rising available amount can look reassuring, but it represents work already performed, not new wealth. The healthiest use is targeted and occasional: identify a real timing problem, access only the necessary amount, and return to the normal pay cycle whenever possible.
My inclusive verdict on Payactiv
After looking at Payactiv through the lens of readability, physical interaction, sensory comfort, and real-world context, I see a focused finance app with a clear reason to exist. It can be genuinely helpful for an eligible worker who needs a controlled way to reach earned wages before the regular payday. The free price and everyone age rating make it approachable, while its established release history and current version show that it is not a brand-new experiment.
The app is a particularly good fit for people facing occasional timing gaps, workers who prefer a focused interface over a full banking suite, and users willing to read each step before confirming a request. It may also be useful for someone who wants to avoid using a credit card for a small, specific expense and can manage the effect on the next pay cycle.
I would be more cautious recommending it to anyone who is short every pay period, expects a universal cash-advance service, or needs a complete budgeting and banking replacement. I would also suggest extra planning for users who require assistive technology or who often use their phone in noisy, rushed, or physically demanding settings. The app may still work well, but it should be tested before becoming part of an emergency plan.
My final advice is simple: decide the purpose before opening the request screen. If the purpose is clear, the amount is limited, and the later budget is already understood, Payactiv can be a useful bridge. If the request is only covering a recurring shortfall, waiting, restructuring expenses, or choosing a different financial tool may be wiser. Its strongest feature is not speed by itself, but the possibility of making earned-pay timing more manageable without pretending that timing changes the total income.
Highlights
- Early access to earned wages can help cover urgent expenses.
- Supports bill payments and money transfers in one app.
- Work-related discounts may add value for eligible employees.
- Budgeting tools can make paycheck planning easier.
- Available on both Android and iOS for convenient access.
Limitations
- Access depends on employer participation and eligibility.
- Some services may include transaction or expedited-transfer fees.
- The app is less useful if your employer is not supported.
- Transfer timing can vary by employer
- bank
- and payment method.
- Requires personal and employment information during setup.
Frequently Asked Questions
01What is Payactiv and how does it work?
Payactiv is a financial wellness app that can let eligible employees access part of their earned wages before the regular payday. After connecting through a participating employer, the app displays available earnings and may offer transfers to a bank account, prepaid card, or other supported option. Availability, limits, and processing times depend on your employer and Payactiv’s current policies.
02Who can use Payactiv?
Payactiv is generally intended for employees whose employers offer the service as a workplace benefit. You normally need to verify your identity and employment details before accessing earned-wage features. Not every employer participates, and eligibility may vary by payroll system, location, employment status, and company rules. Checking with your employer or Payactiv support is recommended before downloading.
03Are there fees for using Payactiv?
Some Payactiv features may be free, while certain delivery methods, transfers, or optional services can involve fees. The exact cost may depend on your employer’s arrangement, the selected payout method, and how quickly you want to receive funds. Review the fee information shown in the app before confirming a transaction, especially when choosing an instant transfer.
04How quickly can I receive money through Payactiv?
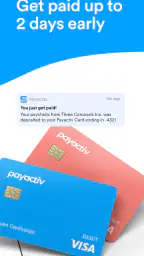
The delivery time depends on the payout method you select and the processing schedules of Payactiv, your employer, and the receiving financial institution. Some options may provide funds quickly, while bank transfers can take longer, particularly on weekends or holidays. The app should show the expected timing and any applicable charge before you submit a request.
05Is Payactiv a loan or does it affect my credit score?
Payactiv’s earned-wage access service is designed to provide access to wages you have already earned, rather than functioning like a traditional payday loan. However, product terms and optional financial services can differ, so you should read the disclosures carefully. Accessing earned wages may also affect the amount received on your normal payday, even if it does not involve a credit check.


